Fourth Quarter FY 2026 IT Spending: What Contractors Might Expect
Published: July 29, 2026
Federal Market AnalysisContracting TrendsForecasts and SpendingInformation TechnologySpending Trends
A conservative estimate suggests that agencies may spend $44B or more on information technology between now and the end of fiscal year 2026.
Federal agencies continue to rely heavily on commercial information technology (IT) contractors and suppliers to meet their operational needs, and Q4 remains the busiest buying period of the fiscal year. The question for contractors heading into the final stretch of FY 2026 is how this year's Q4 might stack up, and where is the money still likely to land.
Based on current spending data and a conservative estimating approach, federal agencies are on pace to obligate roughly $44B on IT contracts in the fourth quarter of fiscal year (FY) 2026. That would put Q4 FY 2026 below the $49.6B agencies obligated in Q4 FY 2025, but agencies could still exceed that estimate. Keep reading to see why.
Total IT Spending Continues to Rise
Total federal IT contract obligations have climbed steadily over the past five years, from $105B in FY 2021 to $128B in FY 2025, a record year.
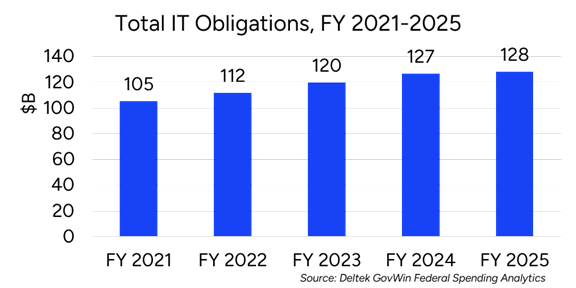
This strong upward trend raises the anticipation for FY 2026 and makes estimating Q4 and total FY 2026 spending levels even more interesting.
Estimating Q4 FY 2026 IT Spending: Methodology and Caveats
This estimate uses a simple, conservative approach. I took each federal agency's total IT contract obligations for FY 2025 and multiplied it by 90% to project a full-year FY 2026 total. I then compared that projected total against what agencies have obligated through the first three quarters of FY 2026 (reported as of July 28, 2026). The difference between the two is the estimated amount left to spend in Q4.
This is a deliberately cautious approach. If agencies spend more than 90% of what they spent last year, both the full-year and Q4 estimates below will understate what actually happens. If they spend less, the estimates will overstate it.
A reporting caveat also applies to Q3. The Department of Defense/War (DoD/W) and its components typically lag in submitting contract obligation data, by as much as three months. That means the Q3 FY 2026 figures for the military services and Defense-wide accounts are likely understated as of this data pull, and the true Q3 numbers, once fully reported, will be higher. This also means the Q4 estimates for those components are likely conservative for the same reason.
The highlighted column in the table below provides an estimate of what each of the top 20 federal departments and agencies might spend on IT in Q4 of FY 2026, if they spend at least 90% of what they spent last year, overall. It is not a perfectly predictive methodology, but it is a good faith effort at conservatively estimating what might be in play for this Q4 buying season.
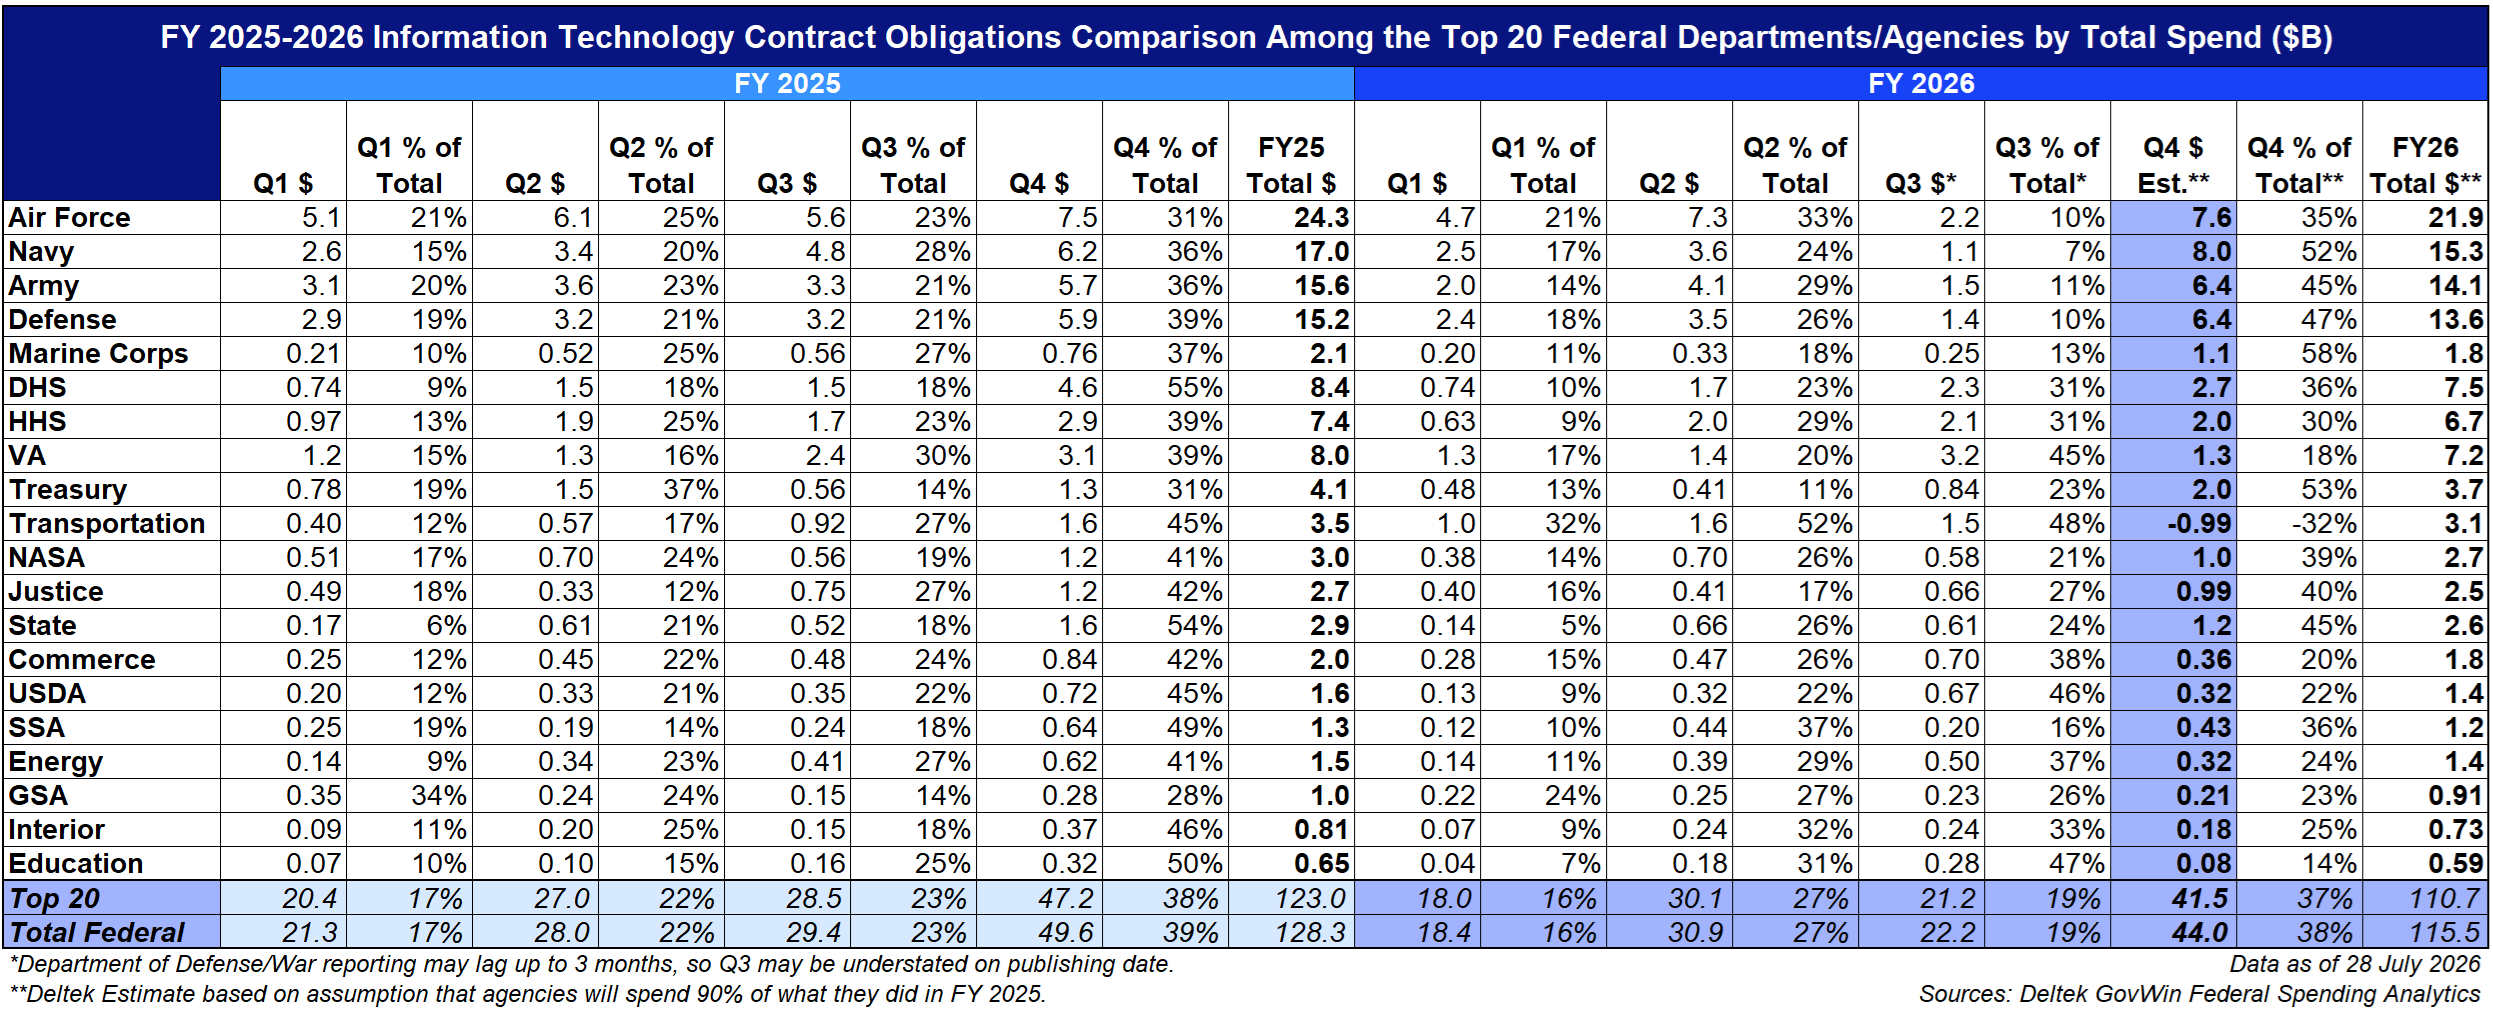
FY 2025 and FY 2026 Quarterly IT Contract Obligations Compared
Within that five-year climb, the twenty top-spending departments and agencies accounted for $123.0B of FY 2025's $128.3B total, or 96%. Within FY 2025, these twenty agencies spent $20.4B, $27.0B, $28.5B and $47.2B in Q1, Q2, Q3 and Q4, respectively. That means 38% of their FY 2025 IT dollars landed in the fourth quarter, compared to 17%, 22% and 23% in Q1, Q2 and Q3.
For FY 2026 to date, the same twenty agencies have reported $18.0B, $30.1B and $21.2B for Q1, Q2 and Q3, respectively. Comparing the individual quarters across the two years shows some noteworthy differences. At 27%, Q2 FY 2026 is running 5% higher than Q2 FY 2025, but Q1 and Q3 are both lower, with the Q3 FY 2026 figure understated due to the DoD reporting lag noted above.
Combined, Q1 through Q3 FY 2026 obligations for the top twenty agencies total $69.2B, about 9% below the $75.9B these same agencies had obligated through Q3 of FY 2025. Does this portend an overall drop in IT spending in FY 2026, or does it point to pent-up demand that will make Q4 even stronger.
Applying the 90% assumption, the top twenty agencies have an estimated $41.5B left to spend in Q4 FY 2026, which is 37% of their projected full-year total, a share consistent with the 38% they spent in Q4 last year. In dollar terms, though, that is about 12% below the $47.2B these agencies obligated in Q4 FY 2025. Looking at all federal departments and agencies together, not just the top twenty, the Q4 FY 2026 estimate comes to $44.0B, also 38% of the projected full-year total.
The lower Q4 FY 2026 estimate traces mainly to the smaller full-year base, since this year's projected total starts out 10% below FY 2025's actual total. That “10% lower baseline” effect is compounded slightly by Q1 through Q3 FY 2026 consuming a marginally larger share of that smaller base, about 62.5%, versus 61.7% for the same period in FY 2025, leaving less both proportionally and in dollars for the fourth quarter.
Transportation’s Accelerated FY 2026 IT Spending – A Methodology Caveat Worth Noting
One agency's numbers illustrate a limit of this 90% approach. The Department of Transportation (DOT) has already obligated more IT dollars through the first three quarters of FY 2026 than 90% of its entire FY 2025 total. The limits of this methodology produces a negative Q4 estimate for DOT, which does not reflect an actual expectation of negative spending. It simply means Transportation is on pace to exceed the conservative 90% benchmark for the year, and its true Q4 obligations, whatever they turn out to be, will add to an FY 2026 total that is already tracking higher than this estimate assumes.
Prospects for the Remainder of FY 2026
If the top twenty agencies spend at least 90% of what they obligated in FY 2025, they have roughly $41.5B in IT contract dollars still to award in Q4 FY 2026, and the federal government as a whole has roughly $44.0B. Both projected figures are lower than what agencies spent in Q4 of FY 2025, given the conservative methodology used.
Contractors should not read this as a shrinking market so much as a return to a more typical pace after an unusually large Q4 last year. The share of annual IT spending that lands in the fourth quarter, around 37% to 38%, has held steady between the two years. What has changed is the size of the base from which it is being calculated. Further, DoD/W, with its reporting lags, may still have more Q4 buying activity in the pipeline than these numbers currently show.